Nittobo's T-glass squeeze shows the AI datacenter bottleneck is upstream
Nittobo controls roughly 90% of the global supply of the T-glass cloth that sits inside every advanced AI chip package, and the shortage is now pushing prices up 20 to 30%.
 Rachel NwosuAI, models and technology
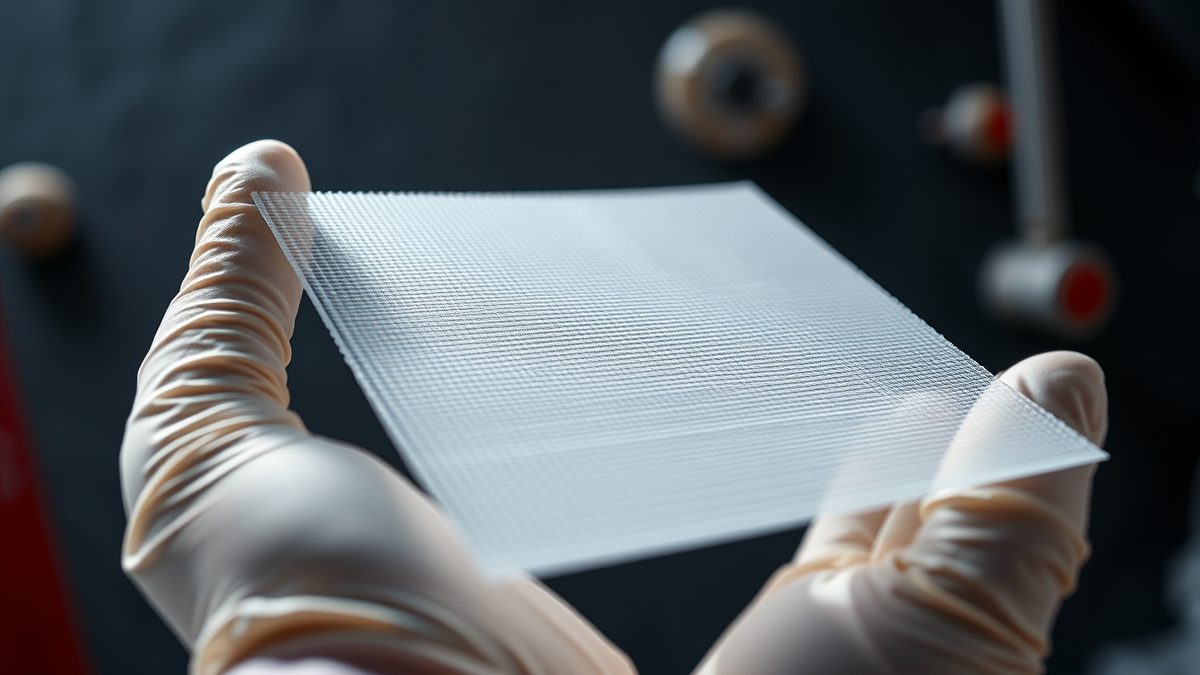
Most of the debate about AI accelerator supply starts with GPUs and foundries. The material that underpins the packages carrying those chips gets less attention. Tom's Hardware reported on 9 March that Nittobo, a Japanese company, controls roughly 90% of the global supply of specialist glass-fiber cloth known as T-glass, and that demand has outrun what the company can make.
T-glass is a low-CTE glass cloth used in the organic core of IC substrates, the interconnect layer between a chip and its printed circuit board. It keeps large, high-heat packages dimensionally stable as they get denser. E-glass does a similar job at lower cost, but it ends up in microcontrollers and older mobile processors. For massive 2.5D and 3D packages, and therefore advanced AI accelerators, T-glass is the preferred option. The material needs specialised electric melting furnaces running between 1,600 and 1,700 degrees Celsius. Melting silica-rich glass, spinning it into yarn and weaving it into ultrathin cloth takes years of investment and expertise to scale. Nobody can spin up a new T-glass production line overnight.
Why the line cannot be switched on faster
Nittobo is tripling capacity at its Fukushima plant in Japan, but the new supply will not reach the market until mid-2027.
The market has already repriced. According to Tom's Hardware, prices have risen between 20 and 30%, while lead times for downstream materials such as copper-clad laminates have stretched from a normal 8 to 10 weeks to beyond 20. "With T-glass supply even more constrained now, suppliers are no longer providing lead times," said Bill Ho, an analyst at Yuanta.
Bilal Hachemi, an analyst at Yole Group who tracks the IC substrate supply chain, told Tom's Hardware Premium that replacing T-glass is not straightforward. It "has specific dielectric and CTE values that work better for the AI chips, especially for the organic core," he said. Hachemi also pointed to the industry's thin margins: "Any increase in demand for build-up materials, ABF material, or T-glass can cause potential shortage, because it's against the basics of this industry."
Bigger packages, more material
What makes this crunch sharper than a normal cycle is who is buying. Hyperscalers are ordering ever-larger chip packages that consume more T-glass per unit. Each generation of a given AI accelerator uses a bigger interposer and a more complex substrate, which translates directly into greater material consumption. Data from Nvidia cited by Tom's Hardware puts interposer sizes at 814mm2 for the Hopper architecture and 1,700mm2 for Blackwell, a 109% increase, with the forthcoming Rubin and Feynman generations scaling further.
Bank of America estimates that Nittobo's electronic materials segment will see sales nearly double from 40.9 billion yen, about $266 million, in 2025 to 87.7 billion yen by March 2028, with operating margins approaching 48%. "Demand for T-glass cloth seems likely to grow more than originally expected," said Takashi Enomoto, a research analyst at Bank of America. "The focus has been on growth in demand for thick T-glass for use in GPU and CPU semi packages, but now ultra-thin T-glass demand is likely to rise on a shift from E-glass to ultra-thin T-glass in leading-edge devices."
The scramble for allocation has started. Hachemi described Nvidia going directly to an upstream material supplier as unprecedented. "For the first time, we are seeing Nvidia, the end customer, reaching out to the upstream material suppliers to secure the capacity and make sure they will get it," he said.
Nittobo is outsourcing to a competitor
The company is not standing still. Beyond the Fukushima expansion, Nittobo is doubling raw yarn capacity at its Taiwan plant and shipping yarn back to Japan for cloth manufacturing. It has also struck a collaboration deal with Nanya Plastics to outsource some weaving.
That deal is itself a signal of how tight the market is: Nittobo is partnering with one of its biggest competitors to ease the bottleneck. By 2027, roughly 20% of Nittobo's glass cloth is expected to be woven by Nanya, according to the company's disclosure.
Against that backdrop, the rest of the accelerator pipeline is moving on its own timelines. At Hot Chips 2026, d-Matrix presented its Raptor 3D-DRAM accelerator for generative inference, which stacks a TSMC N4 logic die on top of a 3D DRAM die using 36 micrometre face-to-face stacking. The company says a 72-card scale-up can host a frontier model such as Kimi K3 at 1M context, and it sizes a card at 32GB with 4-bit weights and an 8-bit KV cache.
Microsoft used the same conference to detail its second-generation Maia 200 accelerator, a 3nm chip with 140 billion transistors, 6 stacks of HBM3e, 7TB per second of HBM bandwidth and a 750 Watt TDP, offering 10,000 TFLOPS of FP4 performance. Microsoft said the chip uses all scale-up networking across 128 racks and 6,000 chips, with a custom NIC and interconnect protocol.
These are different answers to the same problem: inference is memory-bound in the decode phase, so bandwidth per watt matters as much as raw compute. The packaging material underneath all of it is where the current constraint sits. Nittobo's capacity will not arrive until mid-2027, and until then buyers are competing for a supply that one company largely controls.
Sources
3- 01Shortages of crucial chip packaging material threatens AI accelerator supplyEN
- 02d-Matrix Raptor 3D-DRAM Accelerator for Generative Inference at Hot Chips 2026EN
- 03Microsoft's Maia 200 AI Accelerator at Hot Chips 2026EN
All figures and quotations in this text come from the sources listed below.
Content prepared by the editorial team with AI assistance.
Rachel Nwosu
Comments
0- No comments yet — be the first.